Let’s talk about something I see every single day:
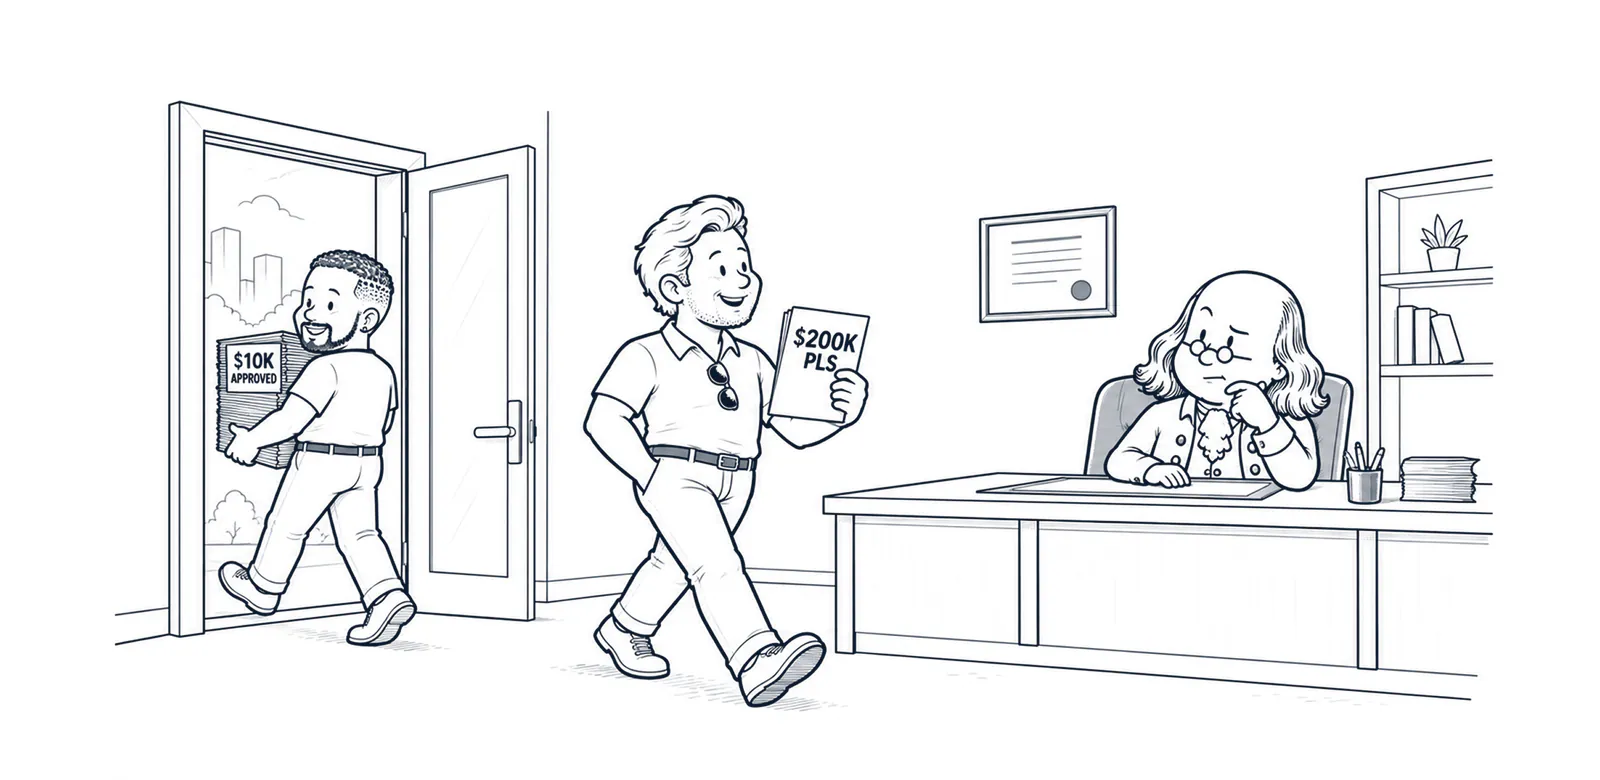
A business doing $5,000–$10,000 a month in revenue applying for $50,000, $100,000, or $200,000 in funding.
Stop.
That’s not how this works.
There are three pillars of financial strength that determine your borrowing power:
Revenue. Time in Business. Personal and Business Credit.
That’s it.
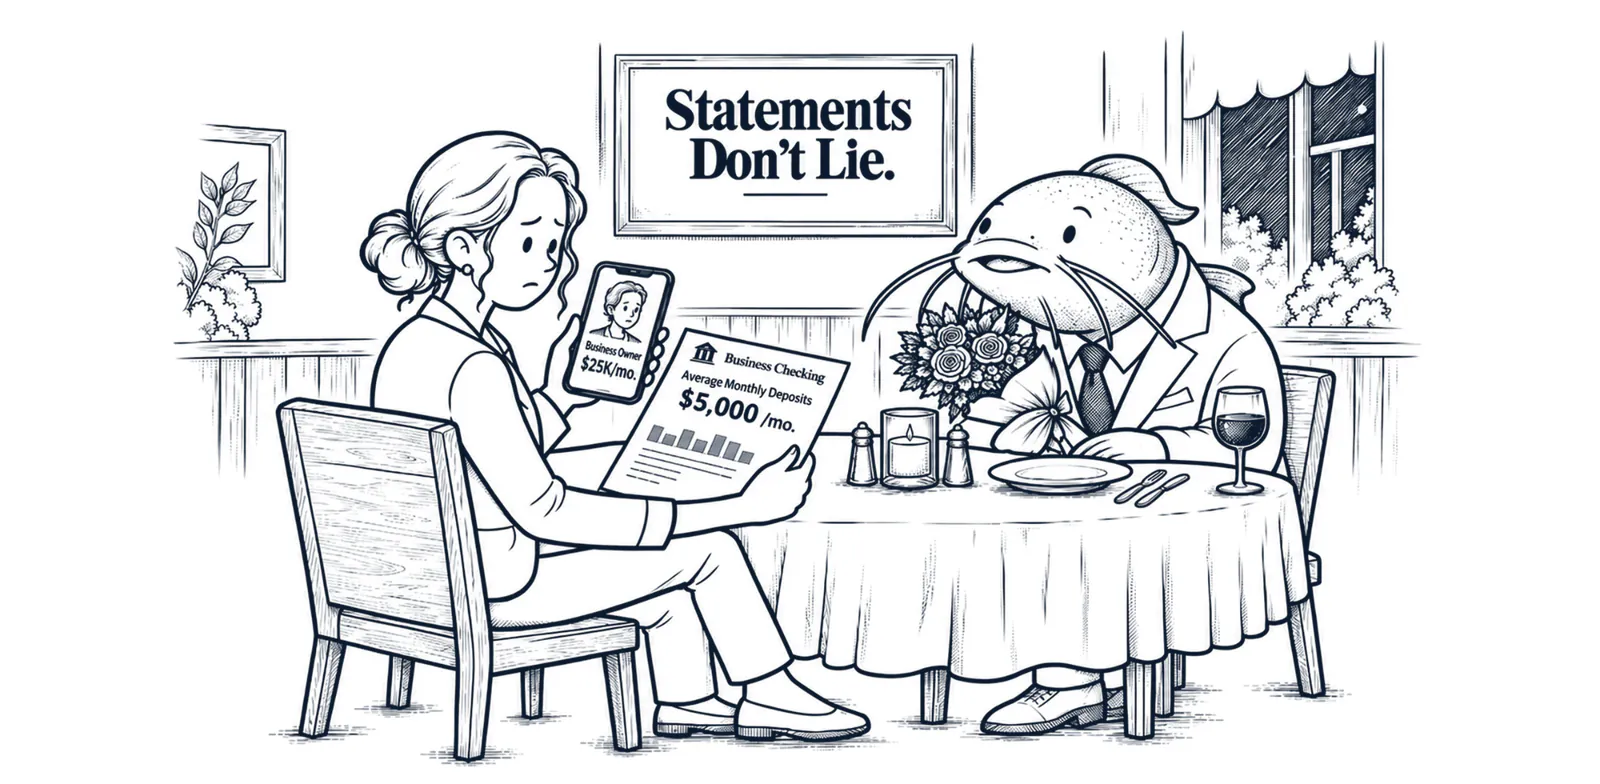
Revenue is what actually hits your business bank account from customers. Not transfers. Not money moved from another account. Real business revenue.
Then you have your time in business and your personal and business credit profile.
Those three things tell a lender how much risk they’re taking and how much capital your business can realistically support.
Here’s the reality:
If you’ve been in business for a short period, you’re doing $5,000–$10,000 a month, and your personal credit isn’t strong, you’re probably not getting a $200,000 business loan.
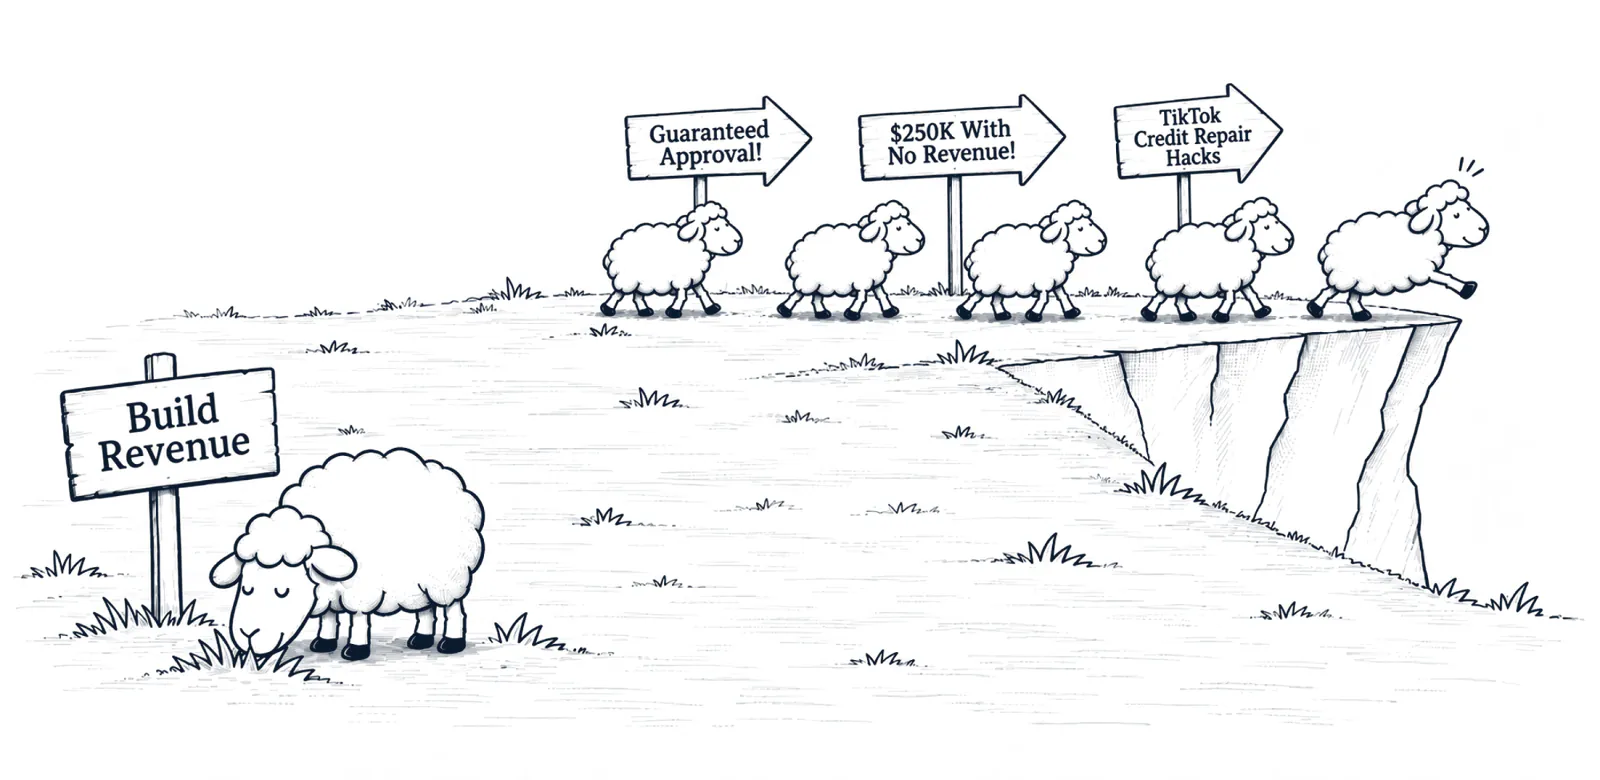
And applying to 30 lenders hoping somebody finally says yes isn’t a strategy.
It’s desperation.
I hear it all the time:
“I just need to find the right lender.”
No.
Sometimes you don’t need the right lender.
You need a stronger file.
Let’s use a simple example.
If your business generates $120,000 in annual gross revenue, a hypothetical line-of-credit program might look at something around 25% of annual revenue, or approximately $30,000, before other underwriting factors are considered.
And that’s assuming the rest of the file supports it: sufficient time in business, strong personal credit, acceptable business credit, profitability, banking history, and everything else the lender requires.
So if you’re doing $5,000–$10,000 a month and asking for $50,000–$200,000, you’re not necessarily being screwed by the lenders.
Your expectations are simply ahead of your business.
And that’s okay.
But fix it.
- Build revenue.
- Build business credit.
- Improve your personal credit.
- Keep clean business bank statements.
- Build time in business.
- Reduce unnecessary debt.
Create a track record that tells a lender:
If you give me this money, I have the ability to pay you back.
That’s borrowing power.
Business funding isn’t a magic pill.
It’s not about finding the one lender willing to ignore everything else.
It’s about becoming the business that lenders actually want to fund.
If you want to know what you need to change to move from where you are today to the level of funding you’re trying to reach, reach out to me.
I’ll show you the path.